Homeowners Insurance in South Lake Tahoe: What Buyers Need to Know in 2026
Real Estate Ryan Smith October 16, 2026
Real Estate Ryan Smith October 16, 2026
Yes, but you should shop for it before you write an offer, not after. Wildfire risk has pushed many carriers to limit new policies around Lake Tahoe. On the California side, buyers who can't find private coverage can use the California FAIR Plan plus a "difference in conditions" (DIC) wrap policy. On the Nevada side, there is no FAIR Plan, so a decline from standard carriers sends buyers to the surplus-lines market. Documented fire hardening and defensible space increasingly decide both price and availability.
By Ryan Smith | October 16, 2026
Insurance availability and pricing change constantly. Nothing here is insurance advice. Talk with a licensed insurance broker about your specific property.
A few years ago, insurance was something you ordered during escrow. At Tahoe in 2026, it belongs at the top of your to-do list, alongside your loan pre-approval.
I've seen deals strain because a buyer found the right home, got into contract, and then discovered the premium was double what they'd budgeted, or that their preferred carrier wasn't writing new policies in that ZIP code. Here's how to avoid that.
Wildfire is the main driver. After a series of major California fires, including the Caldor Fire that reached the edge of Meyers in 2021, many insurers pulled back from writing new policies in high-risk areas, raised rates, or tightened underwriting.
The result for buyers:
Fewer carriers quoting new business in parts of the basin
Higher premiums, sometimes two to four times a standard policy for higher-risk homes
More inspections, including roof, vents, and defensible space, before a policy is bound
Wider gaps between a "best case" quote and what a specific house actually costs to insure
This is one of the biggest practical differences between buying in South Lake Tahoe and buying in Stateline or Zephyr Cove.
If private carriers decline a California property, the California FAIR Plan offers basic fire coverage as an insurer of last resort. Most owners pair it with a DIC policy that adds liability, theft, water damage, and the other coverages a FAIR Plan policy doesn't include.
That combination works, but it usually costs more than a single standard policy, and FAIR Plan enrollment statewide has grown sharply.
Nevada: no insurer of last resort
Nevada does not currently have a FAIR Plan. If standard carriers decline a home in Stateline, Kingsbury, or Zephyr Cove, the next stop is the surplus-lines market, which can be more expensive and less standardized. Nevada lawmakers have considered creating a FAIR Plan, and recent Nevada law changes have also allowed policies that exclude wildfire coverage.
If you're comparing homes on both sides of the state line, get insurance quotes on both before deciding. It can change the math more than property taxes. I covered other cost differences in my California vs. Nevada post.
Here's the order I recommend:
Call a local broker early. Before you tour seriously, talk with an independent broker who writes in the Tahoe Basin. Ask which carriers are writing new business and what they require.
Get a quote on the actual address. Once you're interested in a specific home, request a quote with its real details: roof type and age, construction, distance to hydrant, and fire station.
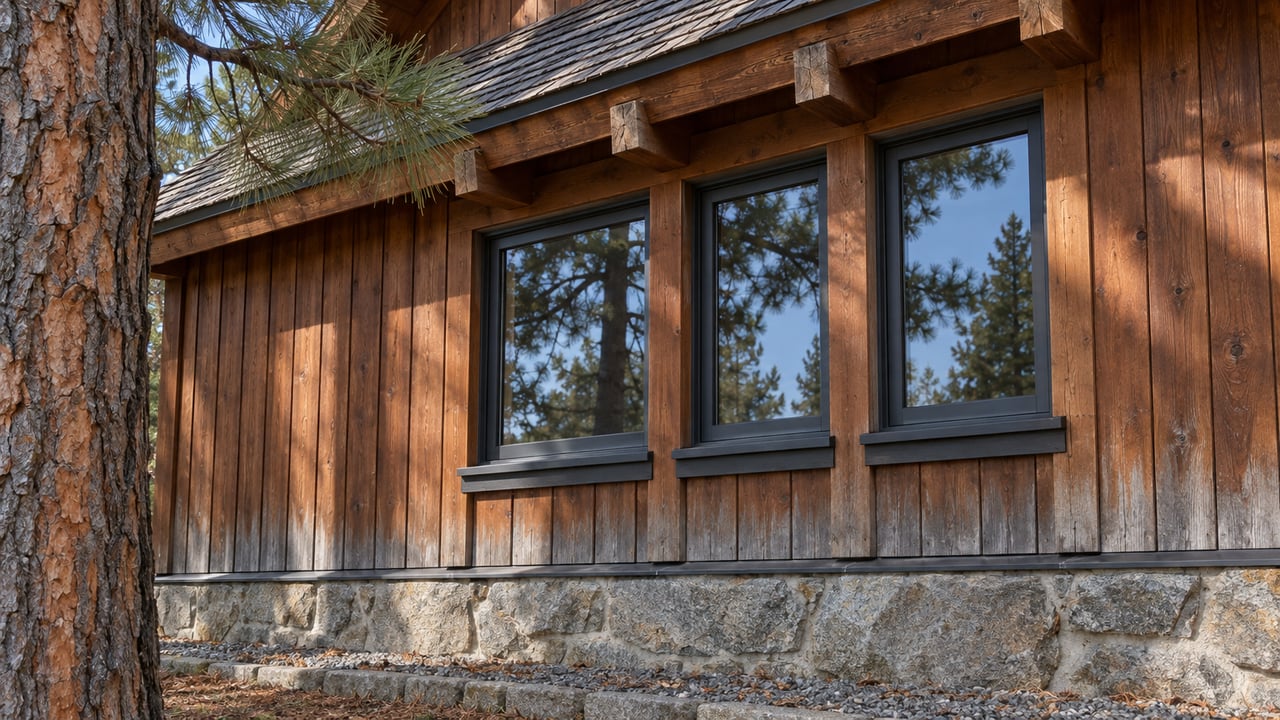
Ask the seller for documentation. Defensible space inspection reports, roof replacement receipts, ember-resistant vent upgrades, and any fire hardening work can lower your premium or make the home insurable at all.
Write insurance into your timeline. Your contingency period should give you time to bind a policy. Your lender will need proof of insurance before closing.
Budget for the real number. Use the actual quote, not an online average, when you calculate your monthly payment.
Insurers increasingly reward documented mitigation. Features that help:
Class A fire-rated roof in good condition
Ember-resistant vents and enclosed eaves
Defensible space that meets or exceeds state and local rules, with a recent inspection report
Non-combustible zone within the first five feet of the house
Proximity to a fire hydrant and a staffed fire station
Updated electrical, plumbing, and heating systems
Homes in neighborhoods that have done community-wide fuel reduction can also benefit. Ask your broker whether any discounts apply.
For sellers: insurance is part of your marketing
If you're selling, assume your buyer will be asking about insurance in their first week of escrow. Have your defensible space report, roof documentation, and any hardening receipts ready. A home that's easy to insure is easier to sell, and that's worth highlighting in your listing.
This is the kind of detail I build into every listing plan, along with the steps in my post on smart strategies to sell your Al Tahoe home near the lake.
How much is homeowners insurance in South Lake Tahoe?
It varies widely by home. Online averages can look modest, but higher-risk homes or homes that require a FAIR Plan and DIC combination can cost several times more. Get a quote on the specific address before you write an offer.
What is the California FAIR Plan?
It's California's insurer of last resort for property owners who can't get coverage in the standard market. It provides basic fire coverage, and most owners add a separate DIC policy for liability and other protections.
Is there a FAIR Plan in Nevada?
Not currently. Nevada-side Lake Tahoe owners who are declined by standard carriers typically turn to the surplus-lines market. Check with a Nevada-licensed broker for current options.
When should I get insurance quotes when buying a Tahoe home?
Before you write an offer, and definitely within your contingency period. Your lender requires proof of insurance to close, and the premium affects your total monthly cost.
Can a seller's defensible space work lower my insurance?
Often, yes. Documented mitigation like defensible space, a Class A roof, and ember-resistant vents can improve insurability and pricing. Ask the seller for reports and receipts.
Insurance is now a front-of-the-line item for Tahoe buyers. Get real quotes early, ask sellers for mitigation documentation, and compare both sides of the state line if you're open to either.
If you're starting your search and want help sorting out the real cost of owning a specific home, call or text me anytime at (530) 545-0045.
About Ryan Smith
I'm a REALTOR® with Compass | Lake Tahoe, based in South Lake Tahoe. I works with buyers, sellers, and investors throughout South Lake Tahoe, as well as the surrounding California and Nevada sides of Lake Tahoe, dual-licensed in both states (CA DRE #02095506, NV #0188892). My partnership Salmon + Smith ranks as a top agents in South Lake Tahoe, covering over $1,000,000,000 in total combined sales. My focus ranges from single-family homes and investment properties, to new construction and luxury properties.
For more content check out our partner site SalmonSmith.com
Real Estate
Can you get homeowners insurance in South Lake Tahoe in 2026?
Real Estate
Is winter a good time to sell a house in South Lake Tahoe?
Real Estate
South Lake Tahoe's residential VHR permits are capped at 900 and new applications are waitlisted. Permits don't transfer at sale. Here's what that means for you.
Real Estate
Under Prop 19, an inherited South Lake Tahoe second home is usually reassessed to market value. Here's how it works, when the exclusion applies, and what families shou… Read more
Realize your real estate dreams with trusted local experts. As your local real estate specialists, we are here to tailor solutions to your individual needs. Connecting with us is more than just transactional—we care deeply about the long-term life cycle of your investment and believe in building a symbiotic relationship. Reach out today, we are ready to assist!